
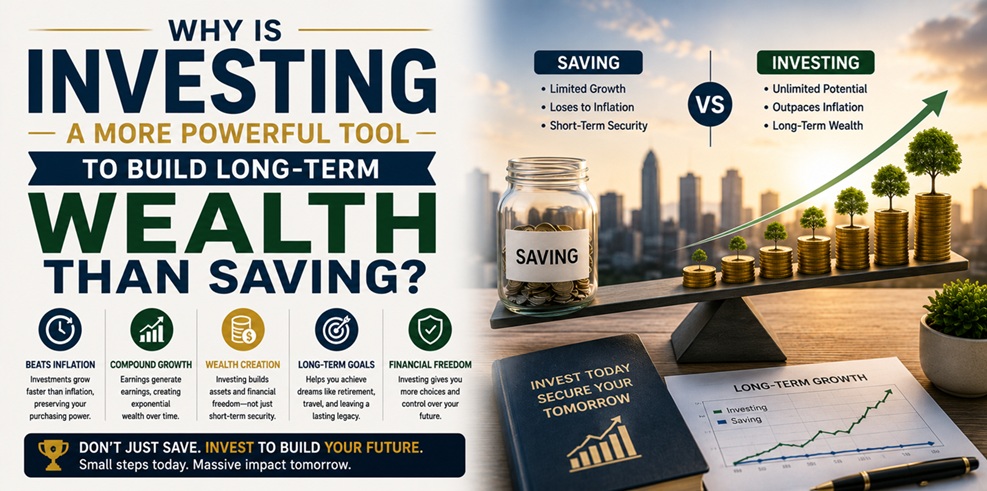
Investing builds long-term wealth far more powerfully than saving alone because of one mathematical reality: investments earn compound returns that historically outpace inflation, while cash savings typically lose purchasing power to inflation over time. A dollar saved in a checking account in 1980 has roughly the same nominal value today, but its purchasing power has fallen by about 75% due to inflation. A dollar invested in a broad-market stock index over the same period grew to nearly $100, even accounting for inflation.
Saving and investing aren’t competitors — they’re sequential. You save first to have capital to invest, and you keep an emergency cushion in cash. But once your short-term needs are covered, every dollar that stays in savings instead of investments costs you the gap between cash returns and market returns. Compounded over a working lifetime, that gap defines whether you retire comfortably or not.
The Core Math
| Strategy | Real Annual Return (after inflation) | $10,000 Over 30 Years |
|---|---|---|
| Cash savings (typical) | -0.5% to 1% | ~$8,600–$13,500 |
| High-yield savings/CDs | 1% to 2% | ~$13,500–$18,100 |
| Bond portfolio | 2% to 3% | ~$18,100–$24,300 |
| Diversified stocks | 6% to 7% | ~$57,400–$76,100 |
Same starting amount. Same time horizon. Dramatically different ending values. The compounding rate is the entire story.
Why Inflation Quietly Wins Against Cash
Even with checking accounts paying 4–5% interest in higher-rate environments, cash typically delivers near-zero real returns over decades. The reason: high cash rates correlate with high inflation. In low-inflation periods, cash rates are also low. The math of cash savings has produced a real return close to zero across nearly every multi-decade period in U.S. history.
A dollar in cash isn’t safe — it’s slowly losing value. The safety is illusion. The risk is just invisible.
How Compounding Multiplies the Gap
Year 1: a 7% investment outperforms a 1% savings account by 6%.
Year 30: the same comparison has the investment at roughly 7.6 times the savings balance — not 1.06x. That’s compounding doing its work over decades.
The math doesn’t help you over 1-year periods. It dominates over 30-year periods.
When Saving Still Wins
Investing isn’t always right. Saving is the right choice when:
- Time horizon is under 3 years. Market volatility can wipe out short-term gains
- Emergency fund — 3–6 months of expenses should stay in cash or near-cash
- Specific short-term goals — house down payment in 18 months, wedding next year
- You don’t have any emergency cushion yet — investing without one means selling at the worst time
For these uses, savings accounts, money market funds, and short-term CDs are the right tools.
The Sequence Most Financial Plans Follow
- Save for a starter emergency fund ($1,000–$2,000)
- Pay off high-interest debt (credit cards)
- Save to build a full 3–6 month emergency fund
- Invest for retirement (401(k) match, then IRA, then more 401(k))
- Invest for other long-term goals (college, second home)
- Save for upcoming short-term goals as they arise
The pattern: save for stability, invest for growth. Both have roles.
The Behavioral Reason Investing Feels Riskier
Saving feels safe because the dollar amount doesn’t drop. Investing feels risky because account balances can fall 20–40% in a bad year. Both feelings are misleading.
A savings account losing 3% real purchasing power per year for 30 years is a 60% loss — quietly. An investment portfolio that fell 40% once and then recovered is whole again. The visible volatility of investments distracts from the invisible erosion of cash.
What Almost All Long-Term Plans Have in Common
Look at any retirement projection that ends with a comfortable outcome and you’ll find the same structure: a small emergency cash buffer, and the rest invested across stocks and bonds for decades. The cash portion provides stability. The invested portion provides growth. Reversing the proportions — most in cash, little invested — almost never produces enough wealth to retire on.
Bottom Line
Saving protects today’s purchasing power. Investing builds future purchasing power. Both are necessary, but for any goal more than 5–10 years out, investing is the tool that does the heavy lifting. The reason investing builds long-term wealth more powerfully than saving isn’t a secret — it’s just compound growth at a rate that outpaces inflation, given enough time. The longer the horizon, the more dramatic the difference becomes.
